

Digital bank Volt secures restricted authorised deposit-taking institution licence
APRA has authorised fintech Volt as a restricted authorised deposit-taking institution, making Volt the first of the digital banks to secure the licence.


The Australian Prudential Regulation Authority (APRA) has authorised fintech startup Volt as a restricted authorised deposit-taking institution (ADI), making Volt the first of the ‘digital banks’ to secure the licence.
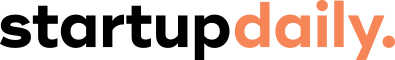
Volt Bank was founded by bankers Steve Weston and Luke Bunbury with the mission to “develop better, more honest products and services that give you greater control of your money”. The company states it will use “technology to adapt to your changing needs and to reduce costs so we can give more back”.
A new license, the restricted ADI licence was itself launched on Friday. It is applicable for a maximum of two years before the restricted ADI must meet the prudential framework in full.
During this time, APRA stated, they are able to conduct “limited banking business while developing their capabilities and resources”, in effect “facilitating entry into the banking sector while not materially lessening entry standards that serve as important protections for the Australian community”.
APRA stated that the granting of a restricted ADI licence will “represent a tangible milestone for applicants at an earlier stage of the licensing process than would otherwise be the case”, in turn assisting restricted ADIs as they look to raise investment or bring on the expertise necessary to attain a full licence.
“As such, the restricted route plays a role in facilitating entry into the banking industry, potentially enhancing competition and outcomes for the Australian public,” APRA stated.
Volt is just one of several fintechs looking to launch as digital banks.
Among them is Pelikin, which has promised customers no account, international card, or ATM fees, “fair” foreign exchange rates, and instant spending notifications. It is also promising to allow users to split bills and pay friends instantly for free, ‘no more clunky bank account numbers’, and ‘a “less banky” looking debit card’.
The startup will also enable users to control and spend in multiple currencies through one app and one debit card.
Meanwhile, Xinja was in February granted an Australian Credit Licence (ACL) from ASIC. It has also applied for an Australian Financial Services Licence (AFSL) from ASIC, and applied to become a restricted ADI from APRA.
The ACL will allow the startup to begin offering home loans over the next few months, while it also looks to push its app and prepaid card in the market. Users must load money onto the card from another account as it doesn’t yet come with its own transaction account.
Xinja does not charge its own ATM fees for ATMs in Australia or internationally. Its app, meanwhile, allows users to open accounts, top up existing transaction accounts, set spending limits, and create and view spend categories.
Image: Steve Weston and Luke Bunbury. Source: Volt.
Comments